Make a room-by-room, photo-backed inventory of everything you own, then store a copy somewhere other than your house. Start today: pick your most valuable room and film a slow walkthrough narrating what you see, then upload whatever list you already have to a cloud...
A weekly review is a short, scheduled ritual where you clear your inboxes, check your calendar, and pick your priorities before the new week starts. The simplest version takes 15 to 20 minutes: dump loose tasks into one list, scan the next seven days, and write down...
Project and client management work best as two linked systems, not one blurred job. Delivery lives on scope, schedule, and resourcing; the relationship lives on trust, expectations, and retention. Agencies that connect them, with a shared client record and a fixed...
Calendar task integration turns your to-do list into scheduled, time-bound calendar blocks so work actually gets done instead of piling up unseen. The fastest path is either a native tasks layer inside your calendar app or an OAuth-based connector syncing a separate...
Quarterly planning means running your business goals on a 90-day cycle instead of a single annual push, reviewing progress and adjusting course every quarter. The practical version that works best: pick a few measurable priorities, assign a clear owner to each, set...
Most people don’t need one framework. They need three, stacked by time horizon: a long-range direction setter like a BHAG or OGSM, a quarterly execution engine like OKRs, and SMART criteria to keep the resulting key results honest and measurable. Skip the strategic...
The PARA method sorts every file, note, and task you own into four folders (Projects, Areas, Resources, Archives) based on how soon you need to act on it. The main payoff is speed: you stop hunting through nested folders and start finding what you need in seconds,...
The best prioritization frameworks for anyone juggling client work, personal goals, and everything in between are the Eisenhower Matrix, the Pareto principle (80/20), the 1-3-5 Rule, time blocking, and a weekly review. Pick one today: schedule a 90-minute protected...
The fastest way to turn emails into tasks is to use your inbox’s built-in conversion feature (Outlook’s drag-to-Tasks or Gmail’s Tasks panel) for one-off items, and automation rules for anything that repeats. Manual capture works fine at low volume; once the same type...
A hobby project planner is a tool, template, or notebook system that helps you capture ideas and, more importantly, always know your single next physical action. Right now, pick one tool, however basic, and write down the very next step for your current project....
How to Track Net Worth: A Practical Step-by-Step Guide
Your net worth is total assets minus total liabilities — and tracking it over time turns a single number into a trend you can actually act on. Here’s how to get a working snapshot in the next hour, then keep it current in under 15 minutes a month.
Quick-start steps:
Pick a date. The first of each month works well. Consistency matters more than the specific day.
List every account balance. Bank accounts, investment accounts, retirement funds, real estate estimates, and any debts you carry.
Subtract total liabilities from total assets. That result is your net worth today.
Save the snapshot. A spreadsheet row, a note, or an app entry — the format is less important than the habit.
Initial setup takes 30–60 minutes. After that, monthly updates run 5–15 minutes once your accounts are organized.
Key Takeaways
Tracking net worth consistently — using the formula, a repeatable cadence, and a tool that fits your workflow — is the single most reliable way to measure real financial progress over time.
Point
Details
Start with the formula
Net worth = total assets minus total liabilities; compute your first snapshot today.
Pick a monthly cadence
Update on the same date each month; three months of decline is a signal worth investigating.
Use a two-sheet template
One sheet for accounts, one for monthly snapshots covers most people’s needs at zero cost.
Trend beats single snapshots
Year-over-year change and CAGR reveal real progress; ignore month-to-month market noise.
LifeDesk unifies the picture
LifeDesk connects personal and business accounts, tracks snapshot history, and surfaces trends in one app.
Real estate at current market value (not purchase price)
Business equity, if you own a business
Vehicles at conservative resale value
Cryptocurrency at current market price
Liabilities to include:
Mortgage principal balance outstanding
Student loans
Auto loans
Credit card balances
Home equity lines of credit (HELOCs)
Any personal loans or outstanding tax obligations
What to leave out: everyday personal property (furniture, clothing, electronics) and expected future income. Future salary is not an asset you own today.
Business equity is worth including if you have a realistic valuation, but be conservative. An unprofitable side project is not a $200,000 asset just because you hope it will be someday.
AI-assisted property valuation tools can help you get a starting figure for real estate, but always apply a conservative adjustment before entering it into your tracker.*
Step-by-step calculation with a worked example
The math takes three minutes. The setup takes longer because you’re gathering numbers, not doing arithmetic.
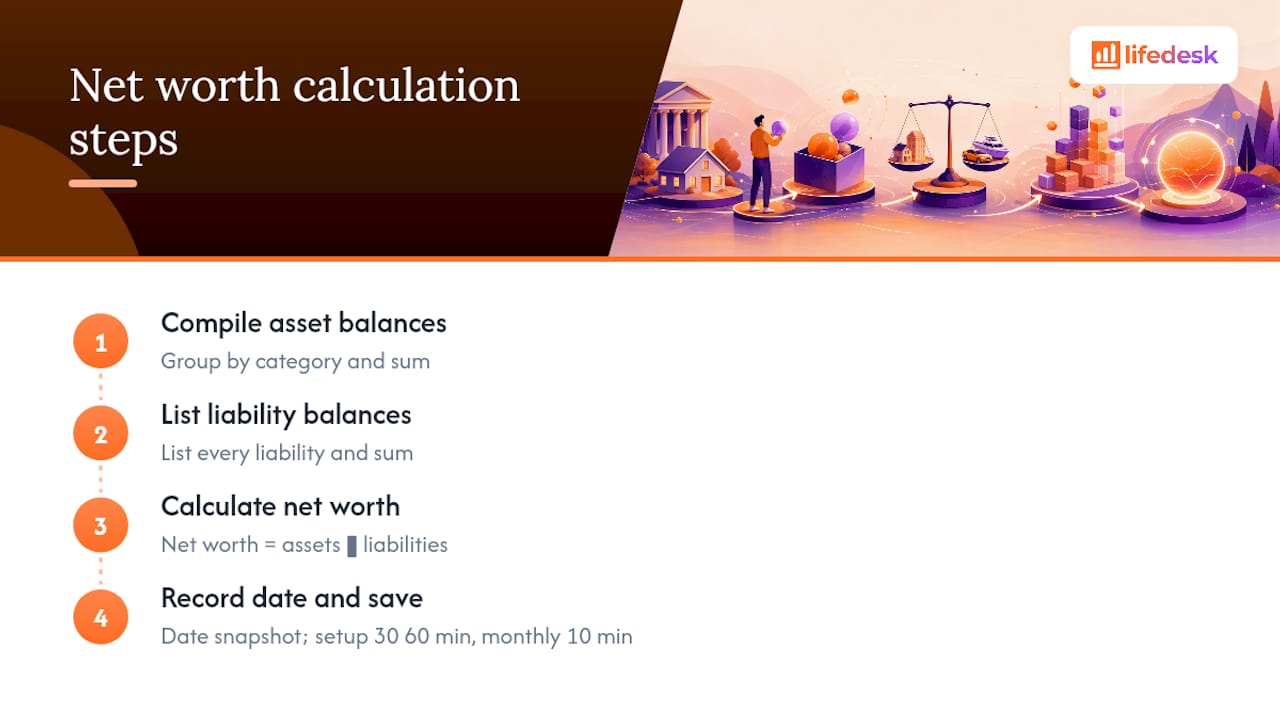
Step 1: Compile asset balances by category and sum them. Step 2: List every liability balance and sum those. Step 3: Net worth = total assets − total liabilities. Step 4: Record the date and save the snapshot.
Here’s what a real snapshot looks like:
One month later, if your brokerage account grew by $1,200 and you paid down $500 in debt, your net worth moves to $163,300. That $1,700 change is the number worth watching.
Time expectations: First setup runs 30–60 minutes, mostly spent locating account login credentials and pulling current balances. Monthly updates, once the structure is in place, take around 10 minutes.
Methods for tracking net worth and how often to update
Three approaches work for most people. The right one depends on how much automation you want and how comfortable you are sharing account credentials with third-party services.
Spreadsheet (manual or automated): You control everything. A two-sheet setup — one for accounts, one for monthly snapshots — is sufficient for most people and costs nothing. The downside is that you enter balances manually each month, which takes discipline. Automation tools like Tiller can pull bank data directly into Google Sheets, cutting a 15-minute manual routine to a 2–3 minute review.
Dedicated net worth apps: Apps that aggregate accounts give you automatic balance updates and built-in charts. Coverage varies: some handle crypto and foreign accounts well, others don’t. You’re also trusting a third party with read-only access to your financial accounts, which is a real consideration.
Bank and portfolio dashboards: Many brokerages and banks now show a net worth estimate inside their own apps. These are convenient but usually only show accounts held at that institution, which gives you a partial picture.
Recommended cadence:
Monthly is the default for most people. Pick the same date each month (the 1st or last business day) and stick to it.
Quarterly works if you have a simple financial picture and low tolerance for maintenance.
Daily is only useful during a specific event — paying off a large debt, watching a volatile investment, or tracking a home sale.
Three consecutive months of decline is a signal worth investigating, not panicking over, but worth understanding.
Pro Tip:Pick one consistent valuation rule for illiquid assets and apply it every month. If you use Zillow’s estimate for your home in January, use Zillow in February too. Switching sources mid-year introduces noise that looks like real change.
Visualization helps. A simple line chart of monthly net worth, with a separate line for total debt, creates a “scissors pattern” when things are going well: net worth rising, debt falling. Tracking year-over-year change alongside the raw number smooths out short-term volatility.
How to choose a net worth tracking tool
Before committing to any app or spreadsheet system, run through this checklist. It takes about a minute and will save you from switching tools six months in.
Security and privacy:
Does the app use bank-level encryption (256-bit AES)?
Are account connections read-only, or does the app have write access?
If you’re linking a brokerage account, understand that SIPC provides limited protection for customers of member broker-dealers if a firm fails — it does not protect against market losses or app-level data breaches.
Does the app have a clear data-deletion policy?
Automation vs. control:
Does it auto-sync balances, or do you enter them manually?
Can you override a synced balance if it’s wrong?
Does it handle crypto, foreign accounts, or business accounts?
Customization and export:
Can you add custom asset categories (business equity, collectibles)?
Does it export to CSV so you can keep a local backup?
How far back does it retain history?
Cost:
Free tier: what’s included and what’s locked behind a paywall?
Paid tiers typically run $0–$10/month or up to $100+/year for bank connections and premium features.
Is there a trial period before you commit?
Criterion
Spreadsheet
Dedicated App
Cost
Free
Free to $100+/year
Auto-sync
No (unless add-on)
Yes
Customization
Full
Limited to app design
Privacy control
Full
Depends on provider
Setup time
30–60 min
15–30 min
History retention
Unlimited
Varies by plan
The FINRED personal net worth tracker is a free, government-hosted option worth bookmarking as a neutral checklist — useful for verifying that you haven’t missed a category.
A ready-to-copy net worth tracker template
Copy this structure into Google Sheets or Excel. Two sheets are all you need.
Sheet 1: Accounts
Sheet 2: Monthly snapshots
Formulas to use:
Total Assets: =SUM(range of asset cells)
Total Liabilities: =SUM(range of liability cells)
Net Worth: =Total Assets − Total Liabilities
Change: =Current Net Worth − Previous Net Worth
To adapt for separate business and personal tracking: add a “Type” column to Sheet 1 with values “Personal” or “Business,” then use =SUMIF to subtotal each. This gives you two parallel net worth figures without duplicating the sheet.
Pro Tip:Add an optional “Investable Net Worth” column that excludes home equity. This figure is often more useful for near-term financial planning, since home equity isn’t liquid until you sell or borrow against it.
How to interpret your net worth results
A single number tells you almost nothing. The trend is what matters.
Focus on year-over-year change first. Month-to-month swings in a brokerage account can move your net worth by thousands without reflecting any real change in your behavior. Year-over-year comparison smooths that out. Compound annual growth rate (CAGR) is the cleanest metric for comparing progress across different time periods.
Context shapes what any number means. A $200,000 net worth at age 28 with no home equity and a $60,000 salary is a very different situation than the same number at age 52 with a paid-off house. Age, career stage, cost of living, and whether you own real estate all affect how to read the figure.
Common benchmark questions:
Is $500,000 a good net worth? It depends entirely on your age, liabilities, and cost of living. For someone in their 30s with a mortgage, $500,000 in total net worth including home equity is solid progress. For someone approaching retirement with no pension and high living costs, it may not be enough to sustain 25+ years of withdrawals.
Is $7 million wealthy? By most global standards, yes. In high-cost cities with significant ongoing expenses, it’s comfortable but not unlimited.
For context on where you stand relative to the broader population: according to the Federal Reserve’s Survey of Consumer Finances, median and mean net worth vary significantly by age group, with the gap between median and mean reflecting how concentrated wealth is at the top.
Net worth tracking also catches problems early. Consistent stagnation — three months flat while you’re earning and spending normally — often points to a spending leak or a debt that’s growing faster than you’re saving.
Consider tracking both total net worth and investable net worth (excluding illiquid home equity) side by side. The gap between the two tells you how much of your wealth you can actually access without selling your home.
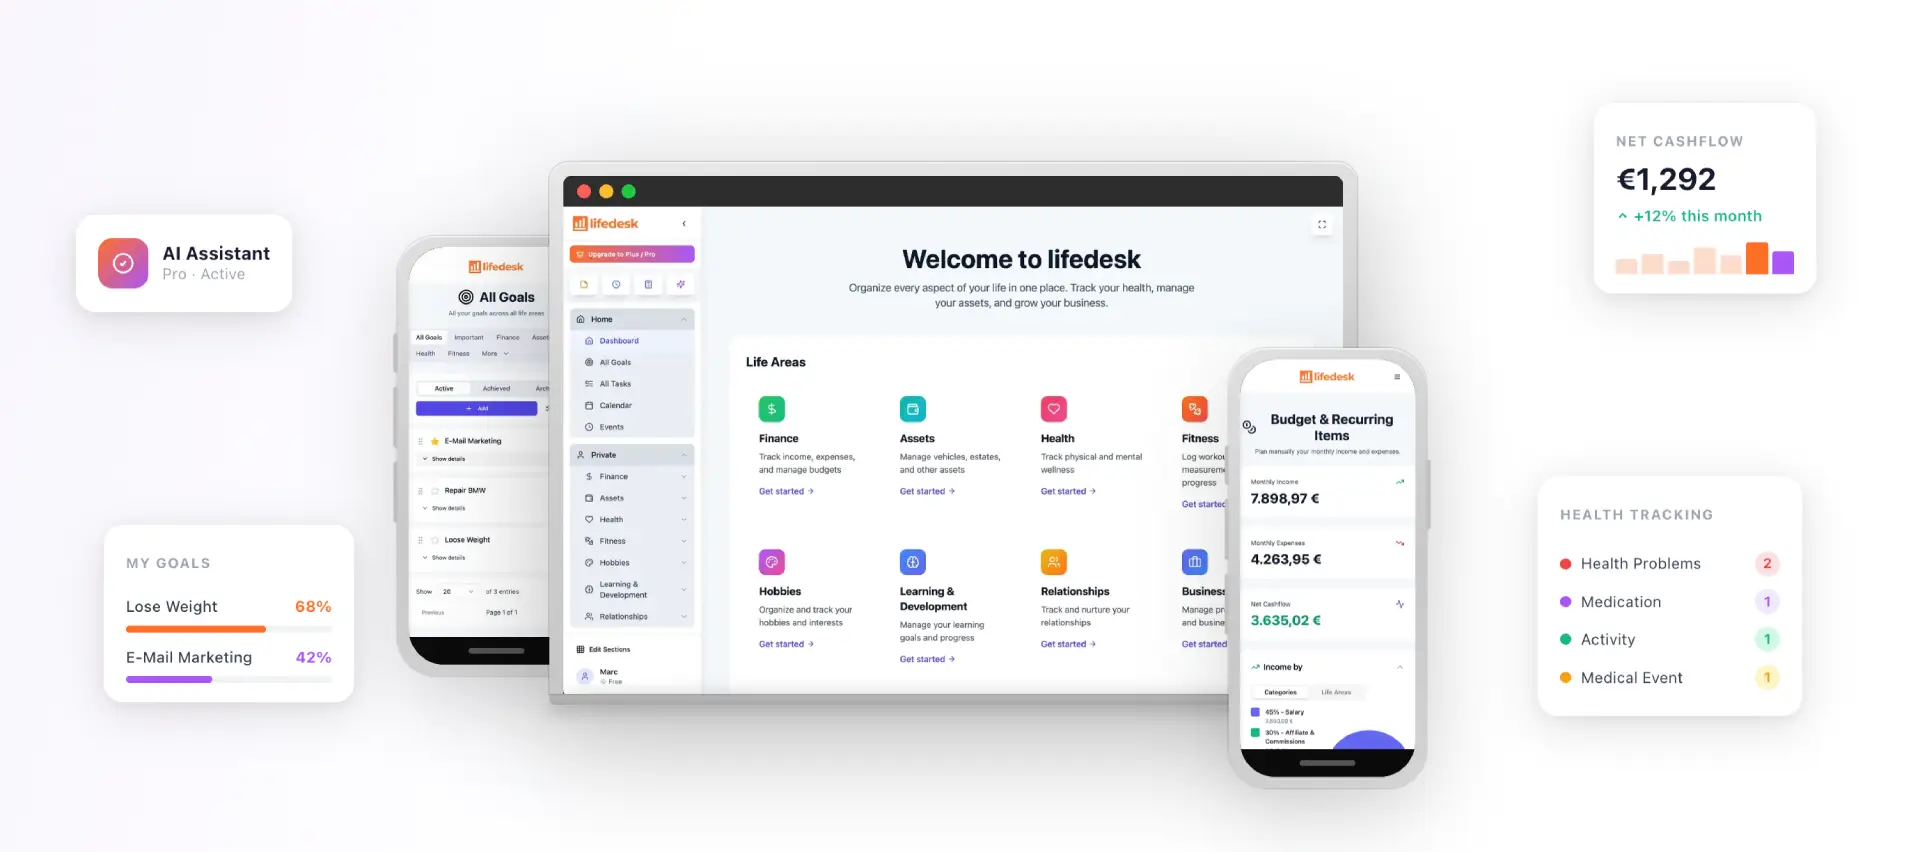
How LifeDesk helps you track net worth in one place
For freelancers and solopreneurs managing both personal finances and business income, the hardest part of net worth tracking isn’t the math. It’s keeping personal savings, client receivables, and business expenses in separate mental buckets while still seeing the full picture.
Account grouping: Organize personal and business accounts separately, then view combined or split totals.
Manual and bank-linked balances: Enter values manually or connect bank accounts for automatic updates.
Snapshot history and charts: Monthly net worth history with visual trend lines, so you can see the scissors pattern without building it yourself.
Separate personal and business views: A freelancer can track client receivables and business expenses in the business finance section while keeping personal savings and retirement accounts in a separate personal view.
AI assistant: LifeDesk’s built-in AI can surface patterns in your financial data and flag months where spending or debt diverges from your trend.
A practical use case: a freelancer with irregular monthly income can log each client payment as it arrives, track outstanding receivables as a current asset, and watch how project income affects net worth month over month — all without switching between a budgeting app, a spreadsheet, and a time tracker. LifeDesk’s time tracking tool pairs with the finance view so billable hours and income stay connected.
For readers who want details on data security and privacy practices, LifeDesk’s privacy documentation is available on the site.
Setup time and costs at a glance
Initial setup (30–60 minutes): Gather account credentials, pull current balances, categorize assets and liabilities, and enter the first snapshot. Most of this time goes to locating accounts you haven’t checked recently.
Monthly update (5–15 minutes): Update balances, enter the new snapshot row, and check the change figure. With auto-sync tools, this drops to 2–3 minutes.
Quarterly review (10 minutes): Compare year-to-date change, check whether any category has shifted significantly (a large debt paid off, a new asset added), and update valuations for illiquid assets.
Typical costs:
Spreadsheet: free
Free basic apps and calculators: free (limited features, no auto-sync)
Paid apps with bank connections: roughly $0–$10/month or up to $100+/year
Premium features to look for at paid tiers: automatic balance sync, crypto support, CSV export, unlimited history, and AI-assisted insights
LifeDesk keeps your full financial picture in one app
Most net worth trackers solve one problem: the number. LifeDesk solves the context around it — tasks, goals, income, expenses, and the financial snapshot all in one place, so you’re not stitching together four apps to see where you stand.
The LifeDesk finance app connects personal and business accounts, logs manual balances, and builds your snapshot history automatically. Freelancers get a combined view of client income and personal savings without the spreadsheet gymnastics. The free plan covers the basics; the Plus and Pro plans unlock bank connections, higher account limits, and the AI assistant. See the full plan comparison and start your first snapshot today at Lifedesk.
This article is general information, not a substitute for advice from a qualified financial advisor. Consult a qualified financial professional about your own circumstances before acting on anything here.
FAQ
How do I track my net worth?
List all your assets (cash, investments, real estate, retirement accounts) and subtract all liabilities (loans, credit cards, mortgage balance). Record the result monthly in a spreadsheet or app to build a trend over time.
Is $500,000 a good net worth?
It depends on your age, cost of living, and liabilities. For someone in their 30s with a mortgage, $500,000 including home equity reflects strong progress; for someone near retirement with high expenses and no pension, it may fall short of a sustainable withdrawal rate.
How many Americans have a net worth of $1,000,000?
Is $7 million net worth considered wealthy?
Yes, by most global and domestic standards. Net worth, though in very high-cost cities with significant ongoing expenses, requires careful planning to sustain long-term.
Can LifeDesk replace a dedicated net worth spreadsheet?
LifeDesk’s finance features cover account grouping, manual and bank-linked balances, and snapshot history with charts — which handles everything a basic two-sheet spreadsheet does, plus business finance tracking in the same app.